
December saw the 10 largest U.S. ports show a 6.4% year over year decrease in inbound volume. This comes after November’s 5.7% decrease and October’s 8.0% decrease. The three-month trailing figures came in at a 6.7% decrease in December, just below November’s 6.8% decrease, both of which were an expansion from October’s 4.8% decrease. Going forward, I anticipate inbound volume into the U.S. both in terms of three-month and monthly figures will show consistent and more pronounced year over year declines into next year in the absence of any changes to the current tariffs.
Returning to U.S. volume trends, inbound loads this December compared to December 2019 were 16.2% higher, which is equivalent to a six-year CAGR of 2.5%. That growth rate measure was below the 3.2% in November but above the 1.7% in October. The underlying trend still points downward.
The medium-term comparisons to the same month in 2019 are important metrics that have the effect of jumping over and therefore netting out the roller coaster impact of the pandemic and getting at the underlying growth rate. The latest actual growth rate of 2.5% compared to 2019 is well below the 3.8% ten-year CAGR that total inbound loads grew in the decade from 2010 to 2020. We are now looking at the real possibility of multiyear declines and will need to arrive at a new equilibrium point before we can then estimate growth. That figure will be below 2.7% per year given the array of factors erected as barriers to trade that did not exist previously.
December’s overall inbound volume of 1,894,836 TEU’s was sequentially 2.0% below November. The sequential decrease last December was lower at 1.2% and another factual indication of the underlying downtrend in the volume data. These sequential comparisons benefit from recency, but the varying number of days in most months injects a 3-10% volume variance and there are also seasonal differences as you go from one month to another. Both of these facts make direct seasonally unadjusted comparisons not particularly relevant.
The 65 months after the beginning of the pandemic effect on container volume began in August 2020 can be thought of as a new era in container shipping. That period first included volume gains from increased consumer spending, then decreases from the rebound of that and more recently underlying volume strength followed by the downtrends evidenced this year. We are now moving into another volatile period that will be overpowered by tariffs pushing volume down. July and August were temporary respites, and declines will return in a more pronounced way based upon the tariffs now in place. December’s overall inbound volume was 4.3% below that 65-month average. East/Gulf Coast ports were 6.9% below their 65-month average while West Coast ports were 1.6% below their 65-month average.
Outbound
Total outbound volume from the U.S. in December decreased 1.2%. In comparison, November was down 4.3% and October was up 16.2%. The latter increase was an anomaly resulting from last year’s short-lived ILA strike that had shippers diverting outbound shipments from East/Gulf Coast ports as the contract deadline approached without resolution. That came after a 0.5% increase in September and a 0.5% decrease in August. That back and forth followed a 2.0% increase in July and a 1.7% decrease in June. While outbound volume has shown that type of erratic pattern on a month-to-month basis for over a year, a more definable downtrend is emerging and is evident by the underlying downtrend in the 0.3% decrease in trailing 12-month volume. Going forward year over year decreases in outbound volume will be more consistent as the impact of countervailing tariffs becomes more pronounced.
Global Perspective
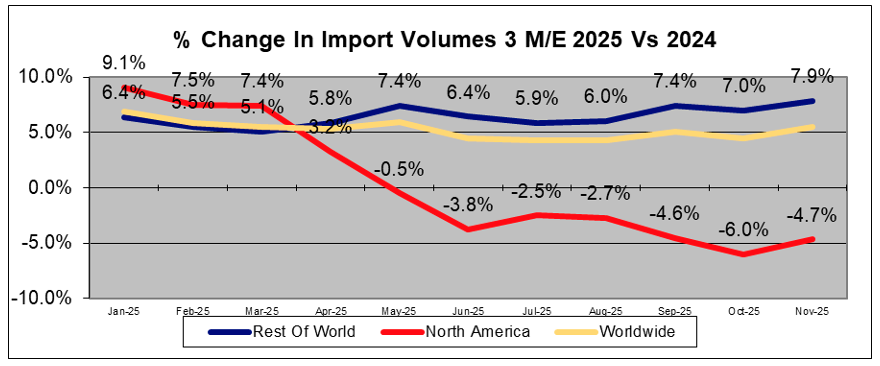
In addition to the downward trends in inbound volume into the U.S. during 2025, another striking trend is the widening gap between trends in inbound volume growth in North America (driven by the five-sixths represented by the U.S.) and the rest of the world. This can be seen in the graph below based on trailing three-month year over year changes during 2025 through November, the last month of available worldwide data.
Based on that metric, North America went from a 2.1 percentage point overperformer at the beginning of 2025 to a 12.5 percentage point underperformer now. For just November itself, the gap was wider at 13.6 percentage points. Volume growth in most regions remains robust and world trade is moving on without the U.S. For instance, while North America inbound volume in November was down 3.9%, global volume grew 7.2%. North America export volume also underperformed growth in global volume, although by not as wide a gap. The differences compared to U.S. volume growth are even wider. Next year will see a continuation and expansion of negative absolute and relative volume trends as 2026 becomes the year of consequences related to tariffs put in place in 2025. The one-two punches of the drag on economic growth from less inbound volume to the U.S. and the inflationary impact of the continuing loads and the consumption tax they represent will be meaningful.
Worldwide container volume grew 7.2% year over year in November, some 12.9 percentage points or 1290 basis points better than the 5.7% inbound volume decline to the U.S. that same month. Another tangible indication of strength in other global markets is the growth of imports in other major regions. Container imports to Africa (up 25.3%), Mideast/India (up 16.4%), South/Central America (up 14.6%) and Europe (up 11.3%) were all robust. November outbound volume from the U.S., the direction that is most directly associated with jobs, was down 4.3% and was lower than and underperformed all major regions. For example, in that same month Mideast/India outbound volume was up 15.0%. As the data shows, world container supply chains have begun to adapt and reconfigure trading patterns faster than I would have thought while U.S. volume languishes and declines.
The full year 2024 saw a 15.2% increase in total inbound loads to the U.S. compared to 2023. With December data now in, that brings total inbound volume for 2025 coming in at 0.3% below 2024. That is a 15.5 percentage point growth swing between those years. We will see a significant decline in 2026 compared to 2025.
This year will be one of the more striking year-to-year changes in U.S. container volume and will continue a downtrend that is the most pronounced since containerization began seven decades ago. These consistent declines related to U.S. container volume are bringing with them reduced growth activity and higher inflation, both adverse economic impacts.
Economic Impact
These container volume reports not only telegraph future economic activity driven by the law of large numbers, but they will be a particularly useful tool into 2026 as they provide data to assess the impact of tariffs on both economic activity and growth as well as inflation.
To put into better context the commercial activity that is impacted from container volume declines, the total value of goods in containers moving in and out of all U.S. ports including the two dozen container ports outside of the Top 10 ports in December was $172.6 billion. That is the equivalent of $2.071 trillion in annualized economic activity.
Whether it involves increases or decreases, material changes in what is a meaningful portion of the U.S. economy will have pronounced positive and negative effects across the economy. For example, a 15% reduction in overall container volume from this point on based on tariffs is possible. Such a decrease would translate directly into a $311 billion reduction in annual commerce for the U.S. What will fill the void is a different issue, but in any case, it will occur later and involve challenges in how to precisely measure it as well as what to attribute it to. But the initial impact both in economic activity and inflation now looks to be significant. It will flow through and ripple throughout the economy, adversely affecting everything that commerce touches and invariably resulting in job losses.
Container volume growth rates and the related trends provide timely macro-economic data that is an early pulse of underlying activity, similar to investor Warren Buffet’s favorite rail car loadings metric. I anticipate that regular readers of my reports will continue to get early insight on economic direction based on actual container volume trends. In 2024, that was related to the strength of the economy. In 2025 and through 2026, that will be the effect of the tariffs and the related economic and inflation impacts.
From being well ahead of the rest of world, the U.S. is now well behind the rest of the world. Worldwide volume growth of 7.2% in November was well ahead of volume growth measures in the U.S. that had inbound volume down 5.7% and total volume down 5.3%. A detailed analysis of how major regions around the world are mitigating the slack in recent U.S. inbound and outbound volume is reviewed in the table on page 17 in this report.
Port Activity
Ports with the strongest December performance were Savannah (down 0.8%), Charleston (down 0.9%) and Norfolk (down 1.3%). The weakest performance came in at Seattle/Tacoma (down 29.7%), Oakland (down 12.8%) and Los Angeles (down 7.9%).
On measures of balance related to inbound versus outbound volume, the East/Gulf Coast ports continue to consistently outperform the West Coast ports. In December, those ports represented 58.6% of exports but only 48.6% of imports. The imbalance at East/Gulf Coast ports is not as pronounced with overall imports 1.89 times overall exports in December. West Coast ports had more imbalances with overall imports 2.84 times overall exports. The highest imbalances in December were Los Angeles at 3.93 times and Long Beach at 3.83 times. The lowest imbalance in December was at Houston at 1.09 times and Oakland at 1.12 times. Overall, the West Coast imbalance metric in December was 49.7% above the East/Gulf Coast metric. December was nearly the same as November’s difference of 49.8% and below October’s difference of 58.0%. It was well below June’s record difference of 76.0%.
Directional growth trends absent the pandemic over the medium term can best be seen in a comparison of actual six-year growth rates based on this December relative to December 2019. Those measures had overall import and export loads diverging by 340-basis points in December, with a growth rate of 2.5% for imports and a growth rate of negative 0.9% for exports. That 340-basis point gap was an 80-basis point contraction from November and below the average of 485 basis points over the previous twenty-seven months. More recently the same metric has been higher as it showed 420, 370, 400, 510, 570, 380, 320, 600, 650, 510 and 500 basis point divergences in November, October, September, August, July, June, May, April, March, February and January.
Using that same six-year CAGR metric, the latest month showed noteworthy differences in coastal performance between imports and exports with the East/Gulf Coast prevailing. Import loads on the East/Gulf Coast had a 3.6% annual growth rate when comparing this December to December 2019. That represents a 200-basis point gap based on a 1.6% annual growth rate for West Coast ports over the six-year period. That is another tangible reminder of the underlying eastward shift in container volume coming into the U.S. The December measure was an expansion of 30 basis points from the November 170 basis points difference. December was slightly below the 210-basis point average over the prior twenty-seven months. That is in comparison to the more recent 170, 190, 260, 80, 70, 160, 520, 220, 80, 210 and 0 basis point differences that metric showed in November, October, September, August, July, June, May, April, March, February and January.
Export loads also had a wide coastal gap compared to import loads in December and that was consistent with the recent history of wider gaps for outbound loads. Exports showed a 0.5% annual growth rate at East/Gulf Coast ports or 330 basis points higher than the negative annual growth rate of 2.8% at West Coast ports. That was a 40-basis point contraction from the 370 level that this measure showed in November. December was below the 456-basis point average difference over the preceding twenty-seven months. The more recent history of that metric shows 370, 390, 540, 350, 370, 420, 500, 420, 360, 360 and 310 basis point differences in November, October, September, August, July, June, May, April, March, February and January.
There continues to be a consistency among imports and exports in terms of individual port performance in comparisons of this December to December 2019 that leapfrogs over the pandemic effect. As has become a consistent pattern among these comparisons of longer-term underlying growth rates, Houston is at the top while Seattle/Tacoma is typically at the bottom.
Container Shipping Pricing & Results
November’s CTS global pricing index is now out and as expected came out at 75. That was up 2.7% from the October level. Compared to its overall 2024 average, that latest monthly index is 21.9% lower. The year-to-date average CTS global pricing index through November is down 16.0% compared to its overall 2024 average.
The November index brought the actual 4Q25 average to 74.7, or 7.0% below the actual 3Q25 average of 80.3 and 7.4% below the actual 2Q25 average of 80.7. From its recent monthly peak level of 118 in July 2024, except for a temporary spike in June, the global pricing index has been declining since then. That July 2024 peak itself resulted from an uptrend since the November 2023 level of 69 and is largely a result of the Red Sea situation.
Note that the CTS global pricing index uses actual 2008 rates as the base set to 100 and they are not inflation adjusted. That level of 69 was the lowest monthly reading over the last five years and approximates where the index was consistently prior to the pandemic. That overall non-inflation adjusted pricing today is less than it was decades ago is another indication that speaks volumes about the cost efficiency of container shipping. The CTS global pricing index level and trend is the most credible measure of sector pricing and the most relevant pricing index to use in any projection of industry results. My quarterly financial reports will continue to be focused on the latest actual industry results but going forward will include more summary projections.
The latest readings on the SCFI index, the most closely followed spot index measure, augment overall pricing insight into the container sector. Pricing in most container lanes involving the U.S. shows trends similar to those in broader measures as the lanes are invariably linked in what is really a single pricing matrix. While there are credibility issues with the various spot pricing indices based on how they are determined and who provides input, they do provide information on the direction and trend of pricing. One example of that is the recent uptick in the SCFI these last few weeks which is highlighted below.
The SCFI began trending down last December and, except for a summer bump due to frontloading, has generally been in a downtrend except for some recent upward movement the past few months. The latest SCFI reading of 1458 on January 23 is 3.0% above the 4Q25 level of 1415 and 1.6% below the 3Q25 level of 1481. In the last 17 weeks, however, the index has increased 30.8% from a reading of 1115 on September 26 which was the lowest the SCFI has been since 12/15/23 when it was at 1094. Note that the late 2023 reading was towards the end of the quarter where the industry reported a small loss as the pandemic effect had ended and it was just before the Red Sea situation provided another notable capacity situation that would sharply push up industry results. What has been pushing up spot rates most recently is capacity reduction in the form of the largest number of cancelled sailings seen since the early days of the pandemic. This is driven by the reduced shipment volume that is occurring as a direct result of the tariffs. This is another indication of the downward trajectory in container volume that will become apparent in the months ahead.

This is an excerpt of the McCown Container Volume Observer, which features an exhaustive deep dive into the facts and figures behind U.S. container shipping volumes, including analysis of monthly trends by port and by direction. The observations and data in the 25-page report include some 20 graphs and tables, providing timely container volume and pricing information. To subscribe to The McCown Report, visit The McCown Report site.
About the author: John D. McCown is an internationally recognized shipping expert with over four decades of experience in the sector. He currently serves as a Non-Resident Senior Fellow at the Center for Maritime Strategy, the think tank of the Navy League. McCown was the co-founder and former CEO of U.S. flag container carrier Trailer Bridge, Inc. He also focused on the shipping and transportation industries from an investment perspective as the transport sector head at a $20 billion hedge fund.


